Sellers hear a lot of numbers before they list: agent pricing opinions, neighbors' sale prices, online estimates and their own sense of what the home should bring. A pre-sale appraisal adds one more number with a different motive behind it, because the appraiser earns the same fee no matter how high or low the value falls. Brian Ward appraises homes for sellers who want to price realistically, decide which improvements are worth making, or anticipate what a buyer's lender appraiser is likely to conclude. The report is written for the owner and can be shared with a listing agent, used to settle a family discussion, or simply kept as a reference point.
What sellers gain from an early appraisal
Pricing too high can lead to long days on market and eventual reductions, while pricing too low leaves equity on the table. An independent value grounds the list price in comparable sales and current competition. It also shows how the home's specific features, such as a remodeled kitchen or a busy street, compare with recent closings. Sellers who receive multiple agent proposals with very different prices often use the report to judge which recommendation fits the evidence. That clarity can also make it easier to hold firm during negotiations.
Before or after repairs
Owners frequently wonder whether to paint, replace flooring or fix a roof before listing. The appraisal values the home as it exists on the inspection date, and Brian Ward can discuss which features most influenced the comparables. In some cases, a value subject to completion of specific repairs can be added, which shows the likely gain if work is finished. That comparison helps sellers decide whether a project is likely to pay for itself or simply delay the sale. Cosmetic projects sometimes add little, while fixing a known defect can remove a buyer objection entirely.
From the visit to the final report
The seller schedules a visit at a convenient time, ideally before staging is completed so the inspection reflects the home's real features. Brian Ward measures the living area, notes condition and updates, and photographs the property. Research focuses on recent sales and active competition in the same pocket of the neighborhood. The report is delivered digitally, and many sellers keep a copy to share with buyers if a lender appraisal later comes in low. Turnaround is confirmed in advance so the report arrives before the listing date.
When values and expectations diverge
Sometimes the appraisal lands below what the seller hoped. That outcome is still useful, because it reveals the issue months before a buyer's lender appraisal would. Common causes include additions without permits, square footage that differs from public records, a dated layout or a location factor such as freeway noise. Knowing these points early lets the seller correct records, gather permit documentation or adjust strategy before the first buyer walks through. An early, honest number is usually less costly than a failed escrow later on.
In the City of San Diego
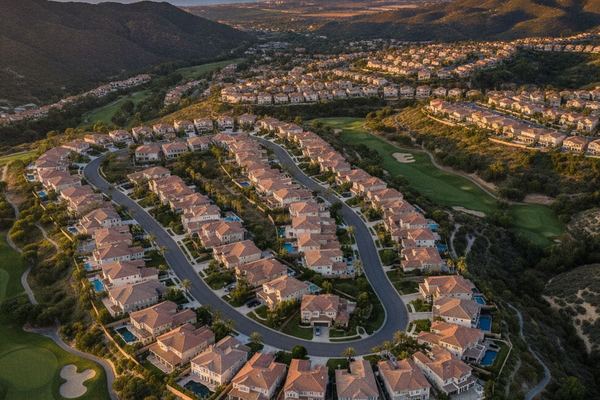
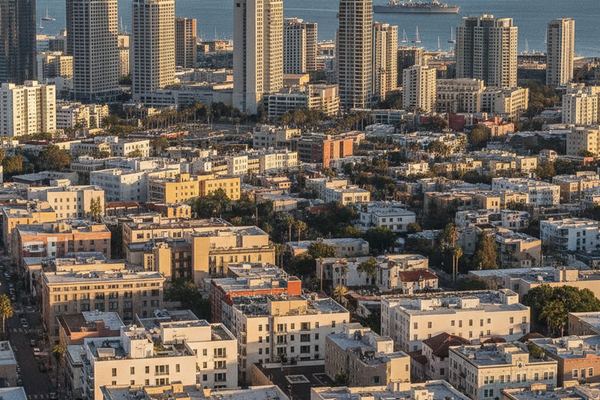
Pre-sale questions in the City of San Diego tend to cluster around a few local features. Coastal properties in Ocean Beach or Bird Rock may carry view premiums that are hard to measure without careful sales selection. Craftsman homes in North Park or Kensington can sell on character, while similar-size homes in Mira Mesa or Rancho Peñasquitos rely more on updates and school attendance areas. Downtown condo owners in the Marina District or East Village face competition from active listings in the same tower. Homes near Montgomery-Gibbs Executive Airport or along the San Diego International Airport flight path also need careful adjustment for noise.
Who orders this report
- Homeowners planning to list
- Owners selling without an agent
- Families deciding whether to sell an inherited home
- Owners comparing competing listing presentations
- Investors selling a duplex or small apartment building
- Sellers worried about buyer appraisal shortfalls
What to have ready
- The planned listing date and any target price
- A list of updates with approximate years
- Permits for additions, ADUs or major remodels
- HOA information and recent special assessments for condos
- Rent rolls and leases for income units
- Any recent pre-listing home inspection
Questions about pre-sale appraisals
Will a buyer's lender accept my pre-sale appraisal?
Generally no. The buyer's lender will order its own appraisal. Your report is still valuable because it shows you, and potentially the buyer, how the value was supported. If the lender's appraisal comes in low, your agent can provide comparable sales from your report through the lender's reconsideration process. That data can be useful during a reconsideration request.
Should I order the appraisal before or after making repairs?
Many sellers order it before repairs so they can see which issues affect value most. If you have already decided on specific projects, the report can include a value assuming completion. Discuss your plans with Brian Ward when you request a quote so the scope matches the decision you are trying to make.
How is this different from an agent's pricing opinion?
Agents provide valuable marketing perspective and know current buyer activity well. An appraisal is a regulated opinion prepared under professional standards by someone who is not compensated by the sale price. Many sellers use both: the agent's view of strategy and the appraiser's analysis of value. Having both perspectives tends to produce a more grounded list price.